The PMC Firm / Module 03
Mandate economics
Fee earned against fee invoiced, expenses booked to the mandate that caused them, receivables aged by client — profitability per mandate rather than a quarterly guess.
- Managing partner
- Finance head
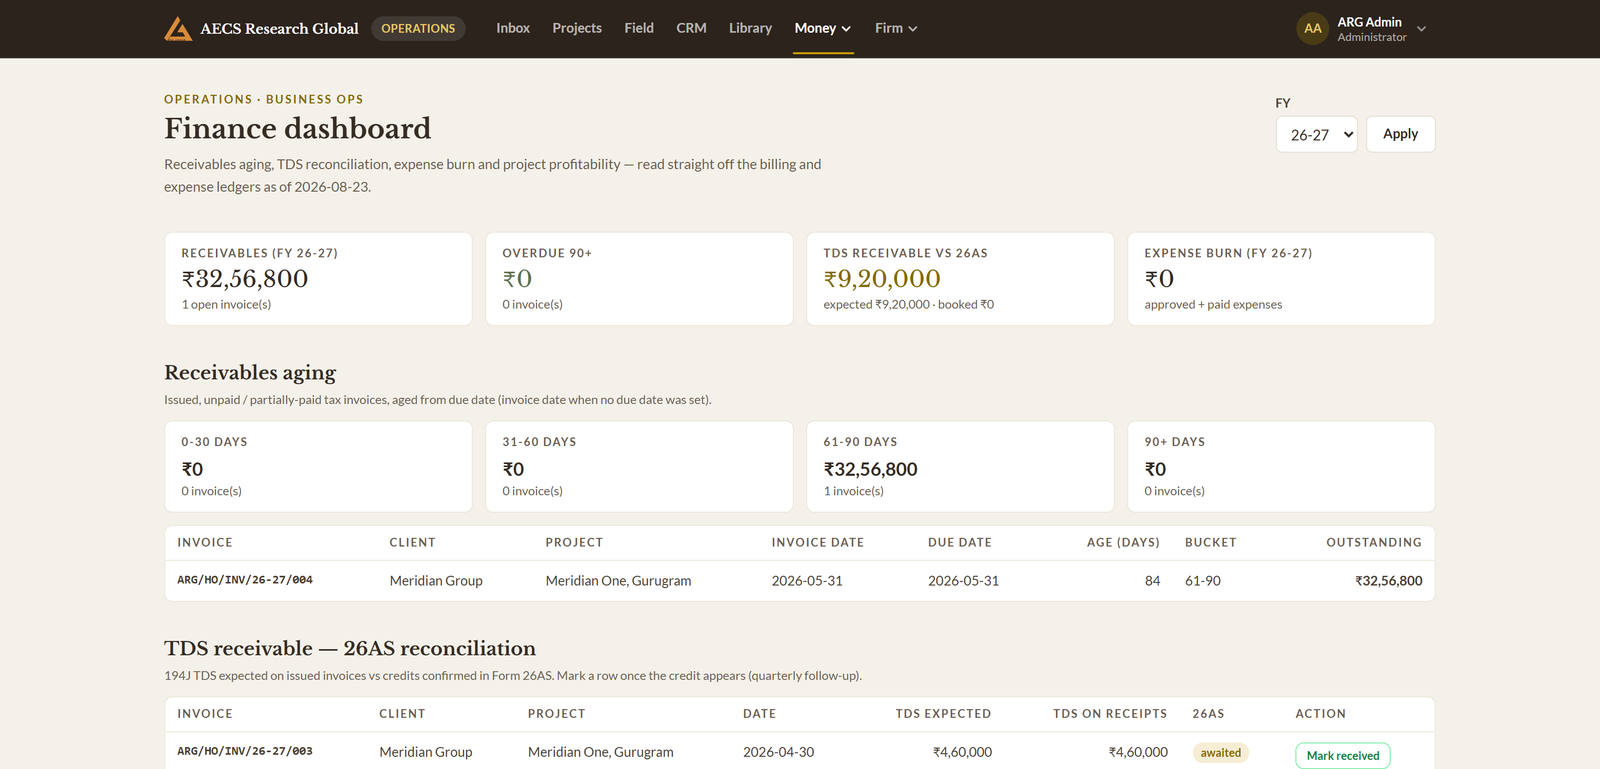
For a firm. Most consultancies know their annual margin and not their per-mandate margin, which means they cannot tell a good client from a busy one. Fee earned, fee invoiced, expenses and collection held per mandate answers the question that actually governs which work you take next year.
What it holds
Fee earned versus invoiced
Stage completion converted to entitlement and set against what has been raised, with unbilled entitlement surfaced by age — the working-capital number a partner should see weekly.
Receivables and collection
Aged outstanding per client with TDS expected against booked, plus dunning rungs that fire on schedule and are journalled whether they send or are suppressed.
Cost of the mandate
Reimbursable and non-reimbursable expenses booked to the project that incurred them, with statutory limits enforced at entry and input credit reconciled.
Statutory position, on one screen
GST output and input, TDS variance, GSTR-1 export and the credit-note position — from the same ledger the mandates run on, so filing and management accounts agree.
What it produces
- Profitability per mandate and per client
- Unbilled and aged-receivable schedules
- Statutory workbooks straight out of the ledger