GST invoicing & site expenses
Tax invoices raised against certified value, receipts and TDS reconciled, site expenses booked with statutory limits enforced — and a GSTR export out of the same ledger.
- Finance
- Accounts
- Site admin
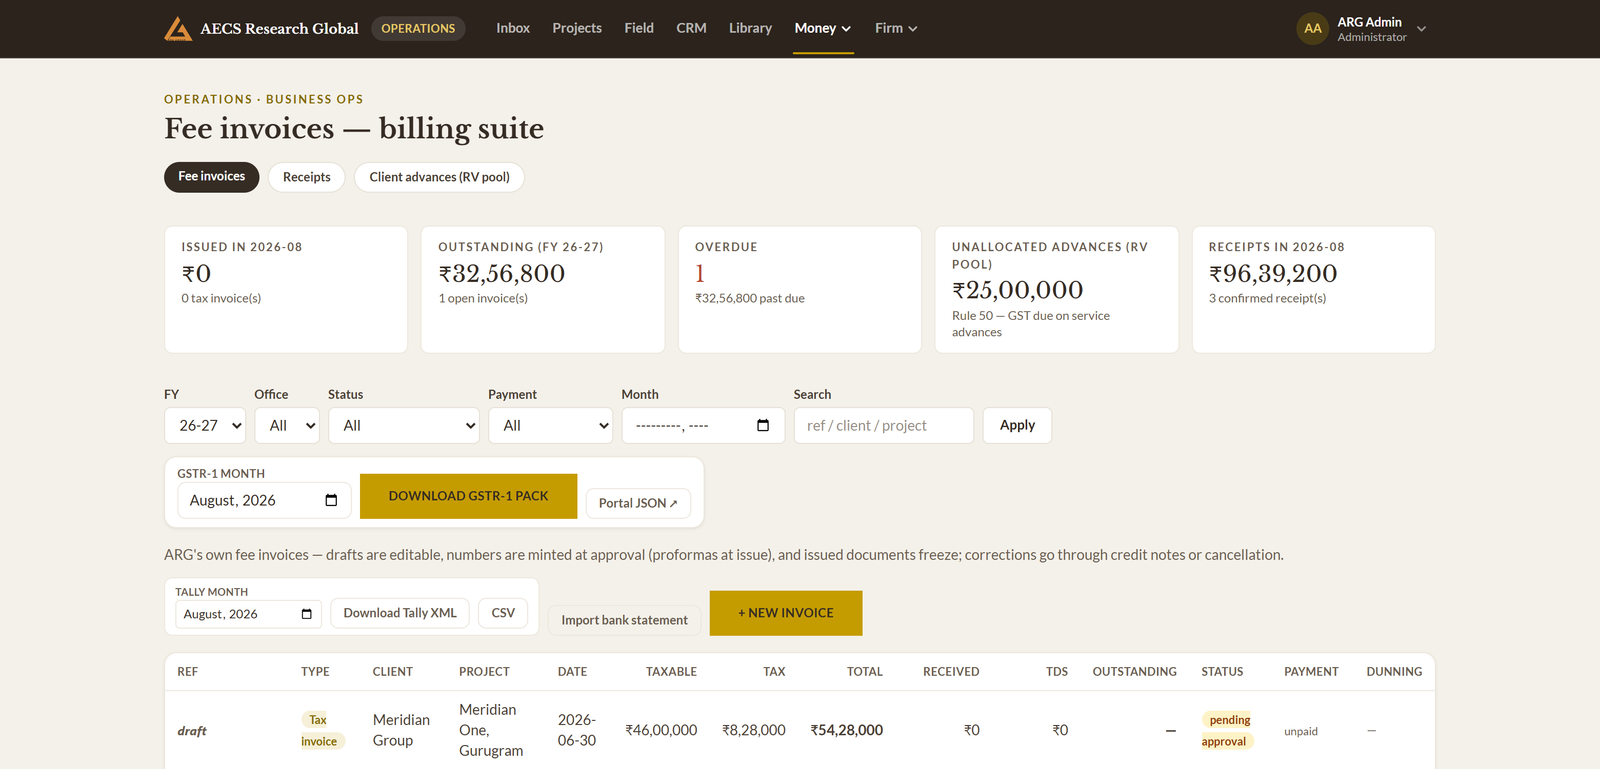
On a contractor's desk. The gap between certified value and invoiced value is where working capital disappears. Raising the invoice from the certificate — and reconciling TDS against what the client actually deducted — is unglamorous and worth more than most features.
What it holds
Invoice against certified value
Rule-46 compliant tax invoices derived from the certificate, with place of supply, HSN/SAC and the works-contract position applied rather than typed.
Receipts, TDS and the ledger
Part payments allocated, TDS and GST-TDS expected versus booked, retention receivable tracked separately, and an unallocated receipt pool that cannot be over-applied.
Site expenses and petty cash
Claims booked to the project with receipt evidence, cash limits enforced at entry including same-day aggregation, and an ITC register that reconciles to the return.
Filing exports
GSTR-1 workbook with amendments and voids from the live ledger, so the return and the accounts agree by construction rather than by reconciliation.
The controls
- Four-eyes on approval; reference mints on approve
- Freeze on issue; corrections ride credit notes
- Append-only receipt and allocation ledger
What it will not allow
- Invoicing more than certified value
- Over-allocating a receipt
- A cash expense beyond the statutory limit